
U.S. Stocks Finish Higher as Treasury Yields Pull Back From Multi-Year Highs
Nivedita Chakrapani, Jadetimes staff
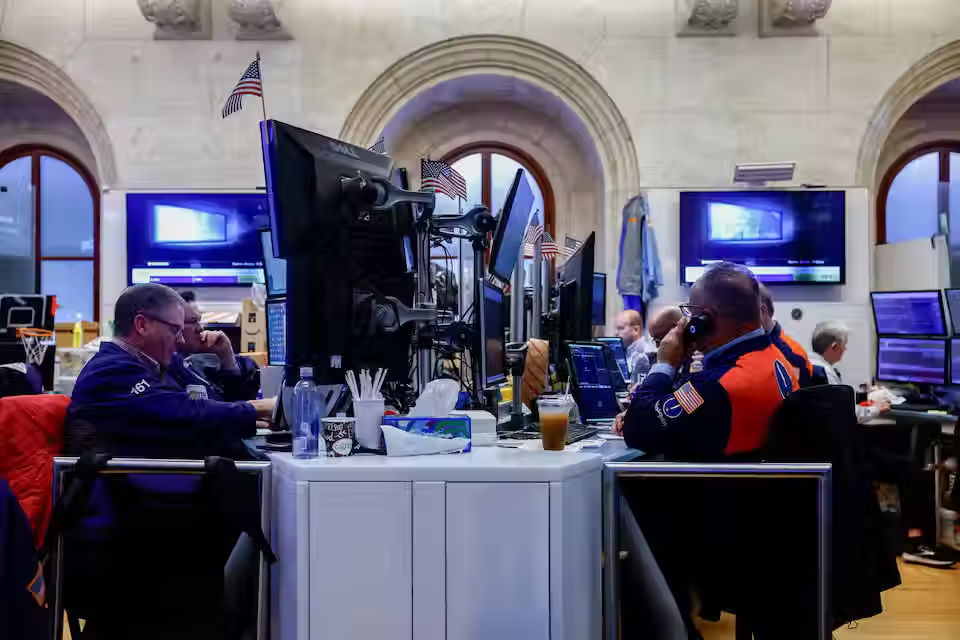
U.S. stocks recovered from early declines on Thursday, closing modestly higher after a sharp rise in Treasury yields reversed course and eased some pressure on equities.
The S&P 500 gained 0.20% to 7,666.48, recovering from a two-week low reached earlier in the session. The Dow Jones Industrial Average added 20.69 points, or 0.04%, to 50,926.74, while the Nasdaq Composite rose 0.04% to 26,871.60.
The market's early weakness came as investors assessed economic data pointing to continued strength in the U.S. economy alongside renewed concerns about inflation.
Treasury Yields Retreat
The benchmark 10-year U.S. Treasury yield briefly reached its highest level since 2002 before moving lower as investors stepped in to buy government bonds.
The decline in yields provided some relief for stocks, particularly after the bond market had experienced significant selling pressure during September.
The two-year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, fell by roughly 10 basis points. It was on track for its largest one-day decline since August 2025.
Federal Reserve Vice Chair Philip Jefferson indicated that policymakers could take their time before making another interest-rate move following September's 25-basis-point increase.
However, Minneapolis Federal Reserve President Neel Kashkari said he expects additional rate increases may ultimately be necessary to slow the economy as policymakers look toward 2027.
Job Market Shows Continued Strength
Fresh labor-market data provided another indication that employment conditions remain relatively firm.
The Labor Department reported that initial unemployment claims fell to 197,000 last week, below economists' forecast of 200,000.
The figure came ahead of the government's monthly employment report and added to a series of recent indicators suggesting layoffs remain relatively limited.
Meanwhile, the Institute for Supply Management reported that its manufacturing PMI edged down to 54.5 in September from 54.6 in August. The report also showed an increase in input prices, adding to concerns about future inflation.
Energy Stocks Lead the Market
The energy sector was the strongest-performing major S&P 500 sector, rising 1.9%.
Oil prices moved higher, with Brent crude settling more than $4 a barrel higher after China suspended fuel exports. The move raised concerns about tighter global energy supplies and potentially renewed inflationary pressure.
Technology stocks also advanced. The technology sector gained 0.8%, while software stocks rose about 1%.
Accenture shares climbed to their highest closing level since March 6 after the consulting company issued a full-year revenue-growth forecast that exceeded analysts' expectations.
Micron Technology also finished about 3% higher after providing a stronger than expected revenue outlook and reporting $32 billion in customer commitments under its supply agreements.
Fed Rate Expectations Shift
Investors have been closely watching inflation and Federal Reserve policy following September's rate increase.
Recent inflation data came in softer than expected, reducing expectations for another increase at the Fed's October meeting.
According to CME FedWatch data cited in the report, markets were pricing in a 28.2% probability of at least a 25-basis-point rate increase, down substantially from 68.6% one week earlier.
The conflicting signals from Federal Reserve officials have left investors balancing the possibility of additional rate increases against evidence that inflation pressures may be easing.
Market Breadth Remains Mixed
Despite the overall gains, market breadth remained uneven.
On the New York Stock Exchange, advancing stocks outnumbered declining issues by approximately 1.23 to 1. On the Nasdaq, the ratio was about 1.04 to 1.
The S&P 500 recorded four new 52-week highs and 41 new lows, while the Nasdaq recorded 41 new highs and 287 new lows.
Trading volume across U.S. exchanges reached approximately 17.25 billion shares, slightly above the 20-day average of 17.19 billion shares.
For investors, Thursday's session highlighted the continued sensitivity of U.S. equities to movements in Treasury yields, inflation data and expectations for the Federal Reserve's next policy decisions.


Comments