top of page

Hadisur Rahman, JadeTimes Staff

H. Rahman is a Jadetimes news reporter covering the USA

Trump
REUTERS/Kevin Lamarque

Several Federal Reserve policymakers are signaling that the central bank may wait for additional economic data before deciding whether to raise interest rates again, sharply reducing market expectations for an increase at the Fed's October meeting.


Recent comments from senior officials, including New York Fed President John Williams and Fed Vice Chair Philip Jefferson, have emphasized the need to assess incoming economic information before making another policy adjustment.


Officials Urge Caution


Williams said earlier this week that there was no immediate need to change the current monetary policy stance. He indicated that another increase could still be appropriate later in the year, but suggested policymakers have time to evaluate economic developments.


Jefferson delivered a similar message Thursday, saying future policy decisions should be based on developments in economic data, the outlook and the balance of risks.


He also noted that rising Treasury yields since the Fed's September meeting indicate that financial markets are reassessing the economic and monetary-policy outlook.


According to Jefferson, policymakers may need additional time and information before determining the appropriate direction for interest rates.


Markets Scale Back October Rate Hike Bets


The comments have produced a significant shift in financial-market expectations.


Traders are now pricing in roughly a 25% probability of a rate increase at the Fed's October 27-28 meeting, compared with approximately 70% earlier in the week.


The shift follows Williams' remarks and was reinforced by Jefferson's comments.


Many major global financial institutions now expect the Federal Reserve to make its next rate increase in December rather than October.


Inflation Remains Above the Fed's Target


Despite the growing expectation that policymakers will wait, inflation remains an important concern for the central bank.


Government data released Wednesday showed that the personal consumption expenditures (PCE) price index increased 3.4% from a year earlier in August.


That remains considerably above the Federal Reserve's 2% inflation target, although the pace was unchanged from July.


The data leave policymakers facing competing considerations: inflation remains elevated, while officials are also assessing the effects of previous rate increases on economic activity.


September Rate Increase


The Federal Reserve raised its target interest-rate range by 25 basis points in September, bringing it to 3.75% to 4%.


At that meeting, policymakers indicated that another rate increase could be appropriate before the end of the year.


However, recent comments suggest officials are not necessarily committed to making that move at the October meeting.


Analysts at Evercore ISI said the comments from Williams and Jefferson represented unusually clear guidance that the Fed was unlikely to deliver consecutive rate increases at its September and October meetings.


Logan Calls September Move a "First Step"


Dallas Federal Reserve President Lorie Logan offered a more hawkish perspective Thursday.


Logan described the September rate increase as a first step and said the Fed could need at least another 50 basis points of rate increases to bring inflation back toward its 2% objective.


She said additional increases could reverse some of the risk-management rate cuts implemented by the Federal Open Market Committee last year.


The Federal Reserve reduced rates by a total of 75 basis points between September and December of the previous year.


What Comes Next


The latest comments illustrate the range of views within the Federal Reserve as policymakers assess inflation, employment and broader economic conditions.


While some officials see a need for additional rate increases, Williams and Jefferson have emphasized that policymakers can take more time before making the next decision.


For financial markets, the immediate focus is likely to remain on incoming inflation and labor-market data, which could influence the Fed's decision-making ahead of its October and December meetings.
Nivedita Chakrapani, Jadetimes staff

Source: ANI
Source: ANI

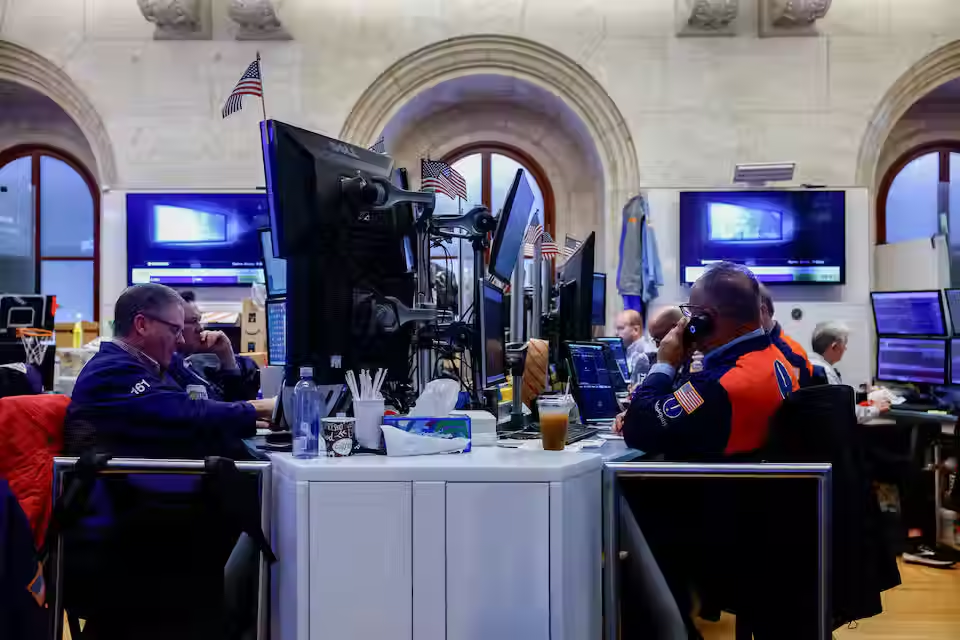
U.S. stocks recovered from early declines on Thursday, closing modestly higher after a sharp rise in Treasury yields reversed course and eased some pressure on equities.


The S&P 500 gained 0.20% to 7,666.48, recovering from a two-week low reached earlier in the session. The Dow Jones Industrial Average added 20.69 points, or 0.04%, to 50,926.74, while the Nasdaq Composite rose 0.04% to 26,871.60.


The market's early weakness came as investors assessed economic data pointing to continued strength in the U.S. economy alongside renewed concerns about inflation.


Treasury Yields Retreat


The benchmark 10-year U.S. Treasury yield briefly reached its highest level since 2002 before moving lower as investors stepped in to buy government bonds.


The decline in yields provided some relief for stocks, particularly after the bond market had experienced significant selling pressure during September.


The two-year Treasury yield, which is particularly sensitive to expectations for Federal Reserve policy, fell by roughly 10 basis points. It was on track for its largest one-day decline since August 2025.


Federal Reserve Vice Chair Philip Jefferson indicated that policymakers could take their time before making another interest-rate move following September's 25-basis-point increase.


However, Minneapolis Federal Reserve President Neel Kashkari said he expects additional rate increases may ultimately be necessary to slow the economy as policymakers look toward 2027.


Job Market Shows Continued Strength


Fresh labor-market data provided another indication that employment conditions remain relatively firm.

The Labor Department reported that initial unemployment claims fell to 197,000 last week, below economists' forecast of 200,000.


The figure came ahead of the government's monthly employment report and added to a series of recent indicators suggesting layoffs remain relatively limited.


Meanwhile, the Institute for Supply Management reported that its manufacturing PMI edged down to 54.5 in September from 54.6 in August. The report also showed an increase in input prices, adding to concerns about future inflation.


Energy Stocks Lead the Market


The energy sector was the strongest-performing major S&P 500 sector, rising 1.9%.


Oil prices moved higher, with Brent crude settling more than $4 a barrel higher after China suspended fuel exports. The move raised concerns about tighter global energy supplies and potentially renewed inflationary pressure.


Technology stocks also advanced. The technology sector gained 0.8%, while software stocks rose about 1%.


Accenture shares climbed to their highest closing level since March 6 after the consulting company issued a full-year revenue-growth forecast that exceeded analysts' expectations.


Micron Technology also finished about 3% higher after providing a stronger than expected revenue outlook and reporting $32 billion in customer commitments under its supply agreements.


Fed Rate Expectations Shift


Investors have been closely watching inflation and Federal Reserve policy following September's rate increase.


Recent inflation data came in softer than expected, reducing expectations for another increase at the Fed's October meeting.


According to CME FedWatch data cited in the report, markets were pricing in a 28.2% probability of at least a 25-basis-point rate increase, down substantially from 68.6% one week earlier.


The conflicting signals from Federal Reserve officials have left investors balancing the possibility of additional rate increases against evidence that inflation pressures may be easing.


Market Breadth Remains Mixed


Despite the overall gains, market breadth remained uneven.


On the New York Stock Exchange, advancing stocks outnumbered declining issues by approximately 1.23 to 1. On the Nasdaq, the ratio was about 1.04 to 1.


The S&P 500 recorded four new 52-week highs and 41 new lows, while the Nasdaq recorded 41 new highs and 287 new lows.


Trading volume across U.S. exchanges reached approximately 17.25 billion shares, slightly above the 20-day average of 17.19 billion shares.


For investors, Thursday's session highlighted the continued sensitivity of U.S. equities to movements in Treasury yields, inflation data and expectations for the Federal Reserve's next policy decisions.

Nivedita Chakrapani, Jadetimes staff

Source: ANI
Source: ANI

The number of Americans filing new claims for unemployment benefits declined last week, reaching its lowest level since mid-July as layoffs remained limited and employers continued to hold on to their workers.


The U.S. Labor Department reported Thursday that initial applications for unemployment benefits fell to 197,000, down from a revised 198,000 the previous week.


The four-week moving average, which provides a less volatile measure of labor-market conditions, also declined. It fell by 2,500 to 200,000.


Weekly unemployment claims are closely watched because they provide an early indication of layoffs and potential changes in employment conditions. So far this year, claims have generally remained below 220,000, a historically low level.


Labor Market Remains Resilient


The latest figures suggest that the U.S. labor market continues to demonstrate resilience despite economic pressures facing businesses and households.


Higher energy costs have added pressure to companies and consumers since fighting involving Iran began on February 28. However, layoffs have remained relatively subdued.


Recent government data also showed that employers posted fewer job openings in August. The Labor Department's Job Openings and Labor Turnover Survey (JOLTS) found that layoffs declined during the month, while the number of workers voluntarily leaving their jobs also edged lower.


Voluntary departures are often viewed as an indicator of workers' confidence in their ability to find other employment.


Gross hiring increased slightly in August, although hiring activity remained relatively weak compared with levels seen in recent years.


Employers Hold on to Workers


Economists say companies appear to be taking a cautious approach to staffing. While businesses are not adding workers at a rapid pace, many are also reluctant to reduce their existing workforces.


Matthew Martin, senior U.S. economist at Oxford Economics, said the latest unemployment claims data remain unusually low and are consistent with JOLTS figures showing limited layoffs.


Businesses may still remember the severe labor shortages that followed the COVID-19 pandemic, when finding workers became difficult across many industries. That experience may be contributing to companies' reluctance to make significant staff reductions.


As a result, the labor market currently reflects a combination of slow hiring and relatively low layoffs.


What the Numbers Mean


The latest unemployment claims figures provide another indication that widespread job losses have not emerged despite slower hiring and broader economic pressures.


The coming employment reports will offer additional insight into whether the labor market can maintain its current stability or whether weaker hiring eventually begins to translate into higher unemployment.

For now, the latest data show that Americans already employed are generally experiencing a relatively high degree of job stability, while employers continue to add workers cautiously.

bottom of page